Business & Freelancer Income Tax Calculator
YOUR YEAR
Tax on what you earn yourself
My income is
Profit after business expenses, before income tax.
KHATA · TAX YEAR 2027
Individual
SET ASIDE EVERY MONTH
Rs 49,167
19.7% of Rs 30 lakh
Rs 2,410,000 after tax
ADVANCE TAX DATES
About Rs 147,500 a quarter
Business tax is paid through the year, not only at filing. Where section 147 applies, advance tax falls due in four instalments; a quarter of this year's estimate is a sensible amount to set aside.
Sep 25
2026
Rs 147,500
Dec 25
2026
Rs 147,500
Mar 25
2027
Rs 147,500
Jun 15
2027
Rs 147,500
Tax customers deducted from your receipts (for example section 153) or advance tax you paid. Export final tax is not counted here.
LOWER IT LEGALLY
Pension, donations and zakat lower the tax
A VPS pension contribution and donations to approved charities earn credits at your average rate (up to 20% and 30% of taxable income), and zakat paid comes off your income.
THE SAME INCOME, OTHER WAYS
Rs 3,000,000 taxed as
As salary
Rs 276,000
9.2%, Employer deducts monthly
As business
Rs 590,000
19.7%, Slabs, on profit
Service export
Rs 30,000
1%, 1% final, gross
PSEB IT export
Rs 7,500
0.3%, 0.25% final, gross
A rough guide: export rates apply to gross proceeds received through a bank and need their conditions (PSEB registration for IT). Final tax on exports applies only if you file, and you can opt out each year when you file.
| Income slab | Rate | Your income in slab | Tax |
|---|---|---|---|
| Up to Rs 600,000 | 0% | Rs 600,000 | Rs 0 |
| Rs 600,001 to Rs 1,200,000 | 15% | Rs 600,000 | Rs 90,000 |
| Rs 1,200,001 to Rs 1,600,000 | 20% | Rs 400,000 | Rs 80,000 |
| Rs 1,600,001 to Rs 3,200,000 | 30% | Rs 1,400,000 | Rs 420,000 |
| Rs 3,200,001 to Rs 5,600,000 | 40% | Rs 0 | Rs 0 |
| Above Rs 5,600,000 | 45% | Rs 0 | Rs 0 |
| Slab tax on Rs 3,000,000 | Rs 3,000,000 | Rs 590,000 | |
| Tax payable on business income | Rs 590,000 | ||
How business income tax works in Pakistan
If you earn from a business or profession, you are taxed on your profit: revenue less the expenses you can show were incurred wholly for the business. Sole proprietors and professionals file as individuals, partnerships and other associations of persons file as AOPs, and both use the same non-salaried slabs. Companies pay corporate tax at different rates and are not covered here.
- Taxable income
- revenue less allowable expenses, less zakat if you pay it
- Slab tax
- fixed amount for the slabs below yours plus the slab rate on the rest
- Surcharge
- 10% of the tax when taxable income is above Rs 10,000,000
- Credits
- pension (section 63) and donation (section 61) credits at your average rate
Tax on exports that qualify for a final tax regime is worked out separately on the gross proceeds and kept out of the slab calculation. Add the two and you have your total tax for the year, which the calculator shows with an effective rate (tax as a share of income) and a marginal rate (the rate on your next rupee of profit).
Two things lower the bill. A pension contribution and approved donations earn credits (the VPS pension calculator shows the tax credit a contribution earns), and zakat you pay comes off your income (the zakat calculator works out how much you owe).
Business and AOP tax slabs, tax year 2027
The slabs for individuals who are not salaried, and for AOPs, are unchanged from tax year 2026. They run from nil up to 45% on income above Rs 5,600,000.
| Taxable income | Tax |
|---|---|
| Up to Rs 600,000 | Nil |
| Rs 600,001 to Rs 1,200,000 | 15% of the excess over Rs 600,000 |
| Rs 1,200,001 to Rs 1,600,000 | Rs 90,000 + 20% of the excess over Rs 1,200,000 |
| Rs 1,600,001 to Rs 3,200,000 | Rs 170,000 + 30% of the excess over Rs 1,600,000 |
| Rs 3,200,001 to Rs 5,600,000 | Rs 650,000 + 40% of the excess over Rs 3,200,000 |
| Above Rs 5,600,000 | Rs 1,610,000 + 45% of the excess over Rs 5,600,000 |
An AOP that is a professional firm, meaning law or its professional body does not allow it to incorporate, pays 40% instead of 45% in the top band. At Rs 12,000,000 that lowers the tax with surcharge from Rs 4,939,000 to Rs 4,587,000. Turn on the professional-firm option under More options if this is you and confirm it with your adviser.
Salary versus business: the same income, different tax
Many people ask what a freelance or business income would cost in tax compared with a job paying the same. The table shows both, using the engine behind the calculator, for tax year 2027.
| Yearly income | Tax as salary | Tax as business income | Extra for business | Business effective rate |
|---|---|---|---|---|
| Rs 1,200,000 | Rs 6,000 | Rs 90,000 | Rs 84,000 | 7.5% |
| Rs 1,800,000 | Rs 72,000 | Rs 230,000 | Rs 158,000 | 12.8% |
| Rs 2,400,000 | Rs 156,000 | Rs 410,000 | Rs 254,000 | 17.1% |
| Rs 3,600,000 | Rs 416,000 | Rs 810,000 | Rs 394,000 | 22.5% |
| Rs 6,000,000 | Rs 1,104,000 | Rs 1,790,000 | Rs 686,000 | 29.8% |
| Rs 12,000,000 | Rs 3,174,000 | Rs 4,939,000 | Rs 1,765,000 | 41.2% |
The gap is large because the salaried table is lighter at every level and, from tax year 2027, has no surcharge. It also explains why business income should be measured after real expenses: each rupee of expense you can document saves tax at your marginal rate, which reaches 30% to 45% at higher profits. For an employee comparing a job offer with freelancing, the salary tax calculator gives the other side of this table.
Freelancers and exporters: the final tax regimes
Two regimes tax export income at a low rate on the gross proceeds instead of the slabs. The tax is deducted by the authorised dealer (your bank) when the foreign exchange is realised.
- IT and IT-enabled services, 0.25%. For software, IT services and IT-enabled services (call centres, graphic design, accounting, data entry and similar) exported by a person registered with and certified by the Pakistan Software Export Board. The reduced rate was extended to tax year 2029.
- Other services exported, 1%. For services rendered outside Pakistan or exported from Pakistan that do not qualify under the IT rule.
The tax is final when you file your return and meet the other conditions in section 154A (no foreign tax credit is allowed). You can choose each year, when you file, not to be taxed under the final regime. Because expenses cannot be deducted from final-tax proceeds, the regime suits exporters whose costs are low compared with their receipts.
The size of the difference is easy to see. Rs 10,000,000 of PSEB IT export proceeds pays Rs 25,000. The same Rs 10,000,000 of proceeds as other service exports pays Rs 100,000, and as business profit at the slabs it would pay Rs 3,590,000. You can also split income: Rs 2,400,000 of business profit plus Rs 8,000,000 of IT exports pays Rs 410,000 at the slabs plus Rs 20,000 final tax, Rs 430,000 in all. Turn on several kinds of income under More options to try your own mix.
Revenue from social media platforms is different. Banks deduct 5% (10% for non-filers) under section 154B, but for a resident creator it is a minimum tax rather than a final one, so you still report the income and pay the slab tax if that is higher.
Advance tax and withholding: what you can adjust
Business tax is not paid in one go on filing day. Customers who are required to withhold deduct tax from payments to you (for example under section 153), and individuals whose latest assessed taxable income, outside salary and final-tax income, reached Rs 1 million, as well as AOPs, pay advance tax in quarterly instalments (section 147). All of these are adjustable: they are credited against the tax computed on your return, and the balance is what you pay or claim back. Enter what has already been withheld or paid in the advance tax card to see your balance.
The final tax on exports is different. It settles the tax on that income, so it does not reduce the slab tax on your other income. Keep your bank advices and withholding certificates, and file by September 30 after the tax year unless the FBR extends the date. For rental income see the rental income tax calculator, and for gains on shares the capital gains tax calculator.
Sources and assumptions
Rates checked October 31, 2026 against the Finance Act 2026 and FBR's tax year 2027 rate card.
- FBR, Income Tax Ordinance, 2001 (amended up to June 30, 2026)
- FBR, Finance Act 2026
- FBR Withholding Tax Rates Card, tax year 2027
- KPMG Taseer Hadi & Co., A Brief of Finance Act 2026
- FBR IRIS e-filing portal
- Method: slab tax on taxable income plus surcharge (section 4AB), credits (sections 61 and 63) and final tax on exports (section 154A)
Results are estimates for information and planning only, not tax, legal or investment advice. Check your own case with a tax adviser, your broker or the official source before acting.
FAQ
Business & Freelancer Income Tax Calculator: common questions
How much tax does a freelancer pay in Pakistan?+
It depends on how the money arrives. A freelancer registered with the Pakistan Software Export Board (PSEB) who exports IT services through a bank pays 0.25% final tax on the proceeds. Other services exported from Pakistan pay 1% final tax. Income that does not qualify is taxed as business income at the slabs, from 15% above Rs 600,000 up to 45% above Rs 5,600,000, on the profit after expenses.
What are the income tax slabs for business individuals and AOPs in 2026-27?+
Up to Rs 600,000: Nil; Rs 600,001 to Rs 1,200,000: 15% of the excess over Rs 600,000; Rs 1,200,001 to Rs 1,600,000: Rs 90,000 + 20% of the excess over Rs 1,200,000; Rs 1,600,001 to Rs 3,200,000: Rs 170,000 + 30% of the excess over Rs 1,600,000; Rs 3,200,001 to Rs 5,600,000: Rs 650,000 + 40% of the excess over Rs 3,200,000; Above Rs 5,600,000: Rs 1,610,000 + 45% of the excess over Rs 5,600,000. The slabs are the same for individuals and AOPs and did not change from tax year 2026.
Why is business income taxed at higher rates than salary?+
The law has two slab tables for individuals. The salaried table applies only when salary is more than 75% of taxable income. Everyone else, including sole proprietors, professionals and freelancers who are not exporters under a final tax regime, uses the higher non-salaried table. On Rs 3,600,000 that is Rs 810,000 as business income against Rs 416,000 as salary.
Is there a surcharge on business income?+
Yes. Individuals and AOPs with taxable income above Rs 10,000,000 pay a 10% surcharge on their tax. The Finance Act 2026 removed it only for salaried individuals. At Rs 12,000,000 the tax of Rs 4,490,000 becomes Rs 4,939,000 with the surcharge.
What is the final tax on exports and do I need PSEB registration?+
Your bank deducts the tax when foreign exchange proceeds reach you. For IT, software and IT-enabled services it is 0.25% and needs registration with and certification by the PSEB; this rate has been extended up to tax year 2029. For other services rendered outside Pakistan or exported from Pakistan it is 1%. The tax is final, so the income stays out of your slabs, if you file your return and meet the section 154A conditions. You can opt out of final tax each year when you file.
Do I still file a return if the tax on my income is final?+
Yes. Final tax treatment depends on filing the return for the year (and the withholding statements, if you are required to file them). Filing also keeps you on the Active Taxpayers List, which matters for withholding rates on your other income and purchases.
How do advance tax and withholding reduce what I pay?+
Tax deducted from your business receipts, such as by customers who withhold under section 153, and advance tax you paid during the year are adjustable. They are credited against your tax for the year, so you pay only the balance when you file, or claim a refund if you paid too much. The final tax on exports is not adjustable and is not credited against slab tax.
Are social media and YouTube earnings taxed differently?+
Banks deduct tax on revenue received from social media platforms: 5% for filers and 10% for non-filers (section 154B, new in the Finance Act 2026). For a resident creator this is a minimum tax rather than a final tax, so you still report the income and the amount deducted is credited against your tax for the year.
Keep going
Related tools
Salary Income Tax Calculator 2026-27
Your salary as a payslip under the Finance Act 2026 slabs, with seven legal ways to pay less tax.
Rental Income Tax Calculator
Tax on rent for individuals and AOPs after section 15A deductions, with tenant withholding and the extra tax on top of your salary.
Capital Gains Tax Calculator for PSX Shares
CGT on listed shares and mutual funds for filers and non-filers, by purchase date and holding period.
PSX guides
Learn the ideas behind the numbers
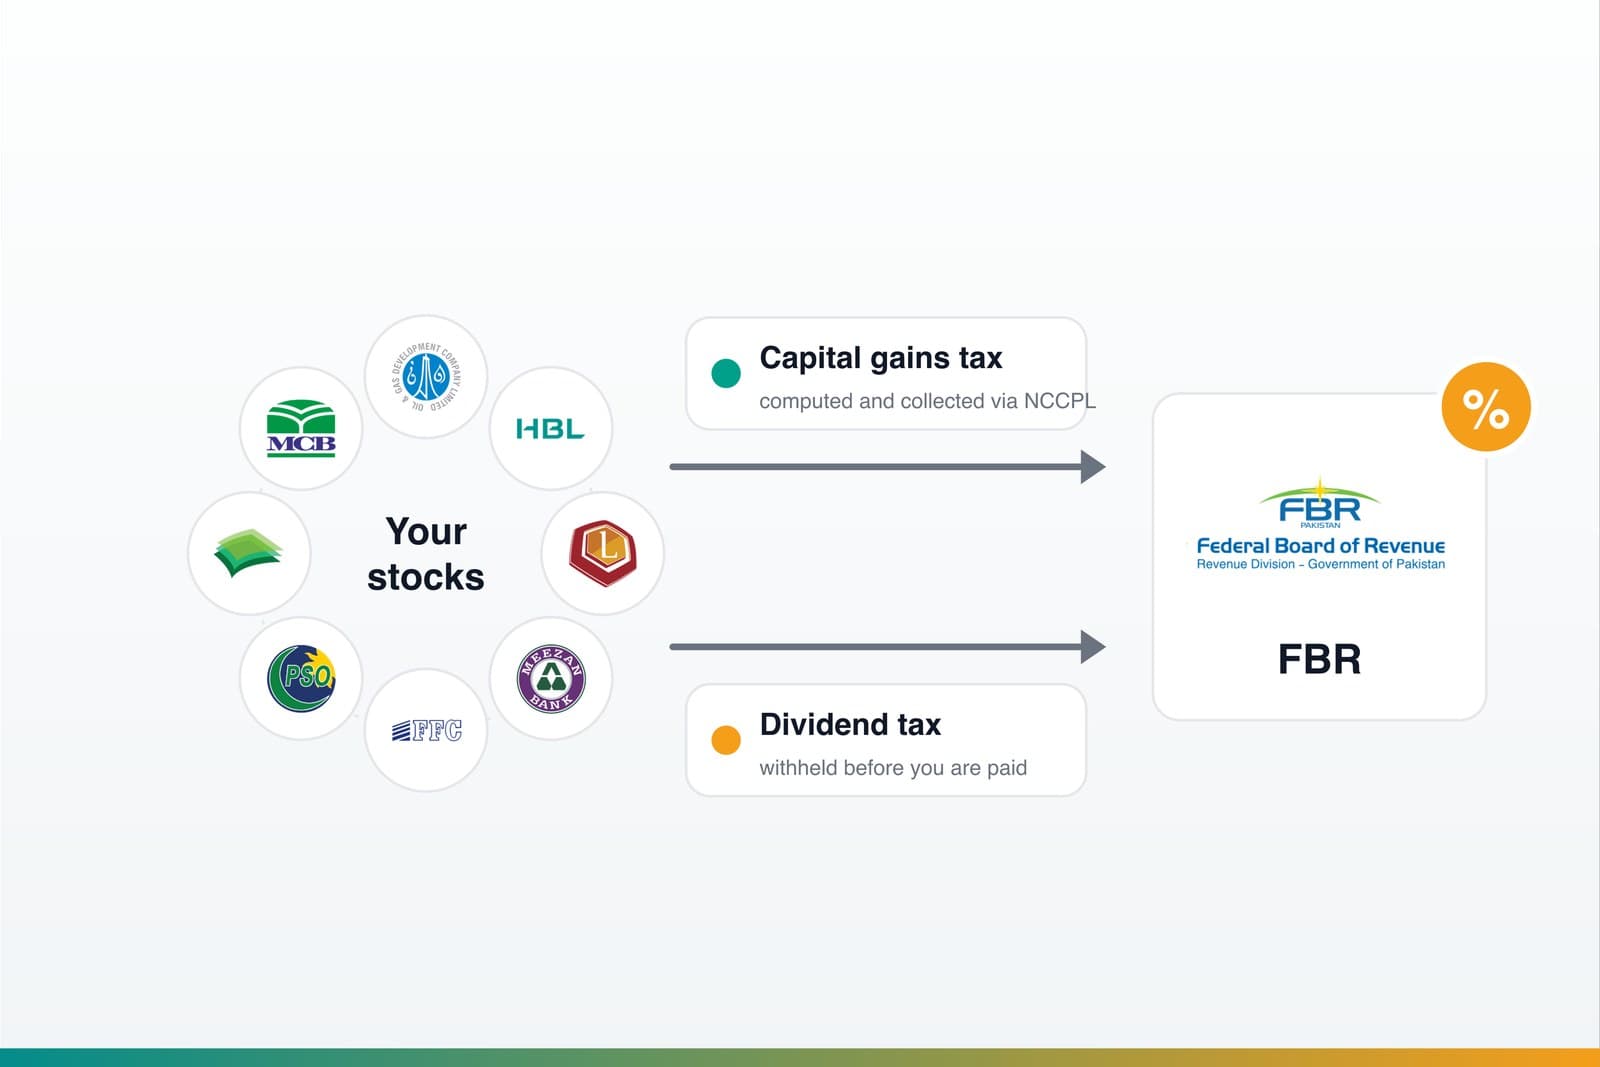
Capital Gains Tax & Dividend Tax on PSX Stocks (Pakistan)
A plain-English guide to how capital gains tax (CGT) and dividend tax work on Pakistan Stock Exchange shares - filer vs non-filer rates, how holding period and acquisition date matter, how NCCPL collects CGT, and what you still have to declare.
Read guide
How to Start Investing in the Pakistan Stock Exchange as a Beginner
A complete beginner guide to investing in the Pakistan Stock Exchange: account setup, brokers, PSX concepts, research, risk management, portfolio tracking and daily market routines.
Read guide
What Is the Minimum Amount Needed to Start Investing in PSX?
Understand how much money a beginner may need to start investing in the Pakistan Stock Exchange, including account requirements, share prices, charges and practical starting ranges.
Read guide