Home Finance Calculator
THE HOME
What will the keys cost you each month?
Priced at KIBOR plus the bank's spread.
Rs 3,000,000. At least 10% must be your own money.
Up to 30 years under SBP rules.
Your rate: 16.05%. KIBOR as of October 30, 2026.
EVERY MONTH
Rs 167,401
On Rs 1.2 crore for 20 years at 16.05%.
All in, the home costs Rs 4.32 crore, 2.88× its price.
CAN YOU AFFORD IT
It takes 42% of your pay: within the limit
The dark mark is the 65% limit on all loan payments.
Largest loan you can get
Rs 1.86 crore
4 lakh
Only know your salary before tax? Work out your take-home pay.
PAY IT OFF FASTER
A little extra each month goes a long way
IF KIBOR MOVES
Floating loans reprice
The rate changes
KIBOR-linked loans reprice on the schedule in your offer letter. Plan for the higher instalment, not only the first one.
Banks decide on your documents and credit record; the limit check is a guide, not an approval. Housing loans also need property insurance or takaful each year. Budget for buyer taxes with the property transfer tax calculator.
- Principal repaid
- Markup paid
Each column is one year of instalments. Early payments are mostly markup; later ones are mostly principal.
How the home finance calculator works
The loan is the property price minus your down payment. The yearly rate is KIBOR plus the bank's spread (the calculator starts from the 1-year KIBOR offer rate, and you can switch to the 6-month one), divided by 12 for each month. The calculator finds the level instalment that repays the loan over your chosen period (the same formula as the loan calculator) and builds the full month-by-month schedule, then compares your instalment with the SBP debt burden limit. Net income means your take-home pay after tax; if you only know your salary before tax, the salary tax calculator works it out.
- DBR
- debt burden ratio: (home instalment + other loan payments) / net monthly income
- Limit
- 65% under SBP housing finance rules (HF-6)
- Largest loan
- the loan whose instalment equals (income x limit) - other payments, at your rate and period
A worked example
A Rs 15,000,000 home with 20% down needs a loan of Rs 12,000,000. At 16.05% (KIBOR 13.05% plus 3%) over 20 years the instalment is Rs 167,401. Over the full term you repay Rs 40,176,245, so the markup is Rs 28,176,245. On a net income of Rs 400,000 that instalment is 41.9% of income, inside the 65% limit; the same income supports a loan of up to Rs 18,637,879.
The period you choose moves the instalment and the total cost in opposite directions:
| Loan period | Instalment | Total markup | Share of Rs 400,000 income |
|---|---|---|---|
| 10 years | Rs 201,390 | Rs 12,166,778 | 50.3% |
| 15 years | Rs 176,663 | Rs 19,799,267 | 44.2% |
| 20 years | Rs 167,401 | Rs 28,176,245 | 41.9% |
| 25 years | Rs 163,538 | Rs 37,061,347 | 40.9% |
| 30 years | Rs 161,855 | Rs 46,267,709 | 40.5% |
Stretching from 20 to 30 years lowers the instalment a little but adds Rs 18,091,464 of markup, because you owe most of the principal for much longer. If your budget allows, a shorter period or extra monthly payments save far more than they cost.
SBP rules for housing finance
The State Bank's Prudential Regulations for Housing Finance (updated August 18, 2026) set the framework every bank must follow:
| Rule | What it says |
|---|---|
| HF-4 Financing tenor | Up to 30 years (10 years for renewable-energy finance) |
| HF-5 Loan-to-value | Maximum 90:10, so at least 10% of the value is your own money |
| HF-6 Debt burden ratio | All monthly loan payments within 65% of net disposable income |
| HF-10 Insurance or takaful | Comprehensive cover on the property for the outstanding amount, with the premium disclosed to you |
| HF-11 Disclosure | Fees, prepayment penalties and the annualized percentage rate shown before you sign; annual statement of principal and markup paid |
These are ceilings and floors for lenders, not what you will be offered. Each bank sets its own spread, documentation and limits, and decides on your income documents and credit record. The State Bank's rules also say banks must use PBA-approved income estimation models for borrowers without formal salary records, which helps self-employed buyers show their repayment capacity.
Mera Ghar Mera Aashiyana, the subsidised scheme
The government's Mera Ghar Mera Aashiyana (also written Ashiana) scheme lowers the rate on a first home. After a revision announced in February and March 2026, reports from Business Recorder and Profit describe these terms: loans up to Rs 10,000,000 for up to 20 years, a fixed 5% end-user rate (replacing the earlier 5% and 8% tiers), the government subsidising the markup for the first 10 years, and eligible homes of up to 10 marla or flats of up to 1,500 sq ft. Applications go through participating banks. The scheme is aimed at first-time buyers and is limited by its budget, so check eligibility with a bank before you plan around it.
| Rs 7,200,000 loan over 20 years | First instalment | Total markup |
|---|---|---|
| Bank loan at 16.05% | Rs 100,441 | Rs 16,905,747 |
| Scheme: 5% for 10 years, then 16.05% (assumed) | Rs 47,517, then Rs 75,185 | Rs 7,524,179 |
The reports we read give the bank price after the subsidy as one-year KIBOR plus 3%, but do not say outright what the borrower pays once the subsidy ends, so the second row is an assumption. Treat it as an estimate and ask the bank for the post-subsidy terms in writing. Beware of unofficial websites and social media posts offering "fast-track registration" for the scheme; apply only through a bank.
Floating rates, extra payments and hidden costs
- Floating rate risk. If KIBOR rises 2 points after 5 years, the example loan costs about Rs 2,902,951 more in total. Test your own case with the If KIBOR moves card.
- Extra payments. Adding Rs 20,000 a month to the example instalment saves Rs 12,797,530 of markup and ends the loan 7.8 years early.
- Buying costs. The down payment is not the only upfront cost. Budget for the bank's fees, property insurance or takaful, stamp duty, registration and the buyer's taxes; the property transfer tax calculator covers the federal advance taxes.
- Renting vs buying. Compare the rent of a similar home with the instalment plus upkeep and insurance before you commit; the monthly outflow can be higher when you buy.
Sources and assumptions
SBP housing finance regulations (updated August 18, 2026), KIBOR (October 30, 2026) and the Mera Ghar Mera Aashiyana terms (March 2026 revision) checked October 31, 2026.
- State Bank of Pakistan, Prudential Regulations for Housing Finance, updated August 18, 2026 (HF-4 tenor, HF-5 loan-to-value, HF-6 debt burden ratio, HF-10 insurance)
- State Bank of Pakistan, KIBOR rates, October 30, 2026 (data: Refinitiv)
- Business Recorder, March 18, 2026: Mera Ghar Mera Ashiana loan size raised to Rs10m, 5% end-user rate, 20 years
- Profit by Pakistan Today, February 28, 2026: ECC approves Rs10 million limit and uniform 5% mark-up
The borrower rate after the 10-year subsidy period is not stated in the reports we found; the calculator assumes the bank price (1-year KIBOR plus 3%). Banks can set a spread and limits of their own. Results are estimates for information and planning only, not tax, legal or investment advice. Check your own case with a tax adviser, your broker or the official source before acting.
FAQ
Home Finance Calculator: common questions
What is the maximum tenure for a home loan in Pakistan?+
SBP's housing finance regulations (updated August 18, 2026) set the maximum tenor at 30 years. Many banks offer 20 to 25 years in practice, and the government's Mera Ghar Mera Aashiyana scheme runs up to 20 years. Your bank's own policy decides what you are offered.
How much down payment do I need for a house loan?+
SBP rules cap the loan at 90% of the property value, so you need at least 10% of the price from your own funds, before registration and other costs. Banks may ask for more depending on the property and your profile. A larger down payment lowers the instalment and the total markup.
How much of my income can go to the home loan?+
Under SBP housing finance rules, total monthly loan payments (the home loan plus all your other consumer loans) should not exceed 65% of your net disposable income. That is the ceiling; banks often apply their own, lower limit. The calculator shows your ratio, the largest instalment it allows, the largest loan and the property price that implies, and the income you need. When the rate is set to rise later (a rate change in the If KIBOR moves card, or the end of the scheme's subsidy), it judges the loan on the highest instalment, not only the first.
What is KIBOR plus spread on a home loan?+
A floating-rate home loan is priced as a benchmark, commonly the 6-month or the 1-year KIBOR (check your offer letter), plus the bank's margin (spread). If the 1-year KIBOR offer is 13.05% and the spread is 3%, you pay 16.05%; the 6-month offer was 12.66% on October 30, 2026. When KIBOR is reset (on the dates in your offer letter) the rate and instalment change. On the example loan, a 2 point rise after 5 years adds about Rs 2,902,951 of markup.
What is the Mera Ghar Mera Aashiyana scheme?+
It is the federal government's subsidised housing finance scheme, run through the State Bank. Reports of the March 2026 revision say loans of up to Rs 10,000,000 for up to 20 years carry a fixed 5% rate for the first 10 years, for a house up to 10 marla or a flat up to 1,500 sq ft. Use the Govt scheme option in the calculator to see the effect. Terms, eligibility and funding can change, so confirm with a participating bank.
Does paying extra each month really help?+
Yes, a lot on a long loan. On the example (Rs 12,000,000 at 16.05% for 20 years), adding Rs 20,000 a month to the instalment finishes the loan in about 12.3 years and saves Rs 12,797,530 of markup. Check for early settlement charges first.
What other costs come with buying a house on finance?+
Beyond the down payment and instalments, budget for the bank's processing and valuation fees, mandatory comprehensive insurance or takaful on the property (SBP rules require it), and the buyer's taxes, stamp duty and registration costs. The property transfer tax calculator on Investify covers the federal advance taxes.
Keep going
Related tools
Loan EMI Calculator
Monthly instalment, total interest and the full repayment schedule for any loan.
Property Transfer Tax Calculator
Advance tax for buyers and sellers (236K, 236C) and capital gains tax on property, filer vs non-filer.
Car Financing Calculator
Monthly instalment on a bank car loan from KIBOR plus spread, down payment and insurance.
PSX guides
Learn the ideas behind the numbers

How to Start Investing in the Pakistan Stock Exchange as a Beginner
A complete beginner guide to investing in the Pakistan Stock Exchange: account setup, brokers, PSX concepts, research, risk management, portfolio tracking and daily market routines.
Read guide
What Is the Minimum Amount Needed to Start Investing in PSX?
Understand how much money a beginner may need to start investing in the Pakistan Stock Exchange, including account requirements, share prices, charges and practical starting ranges.
Read guide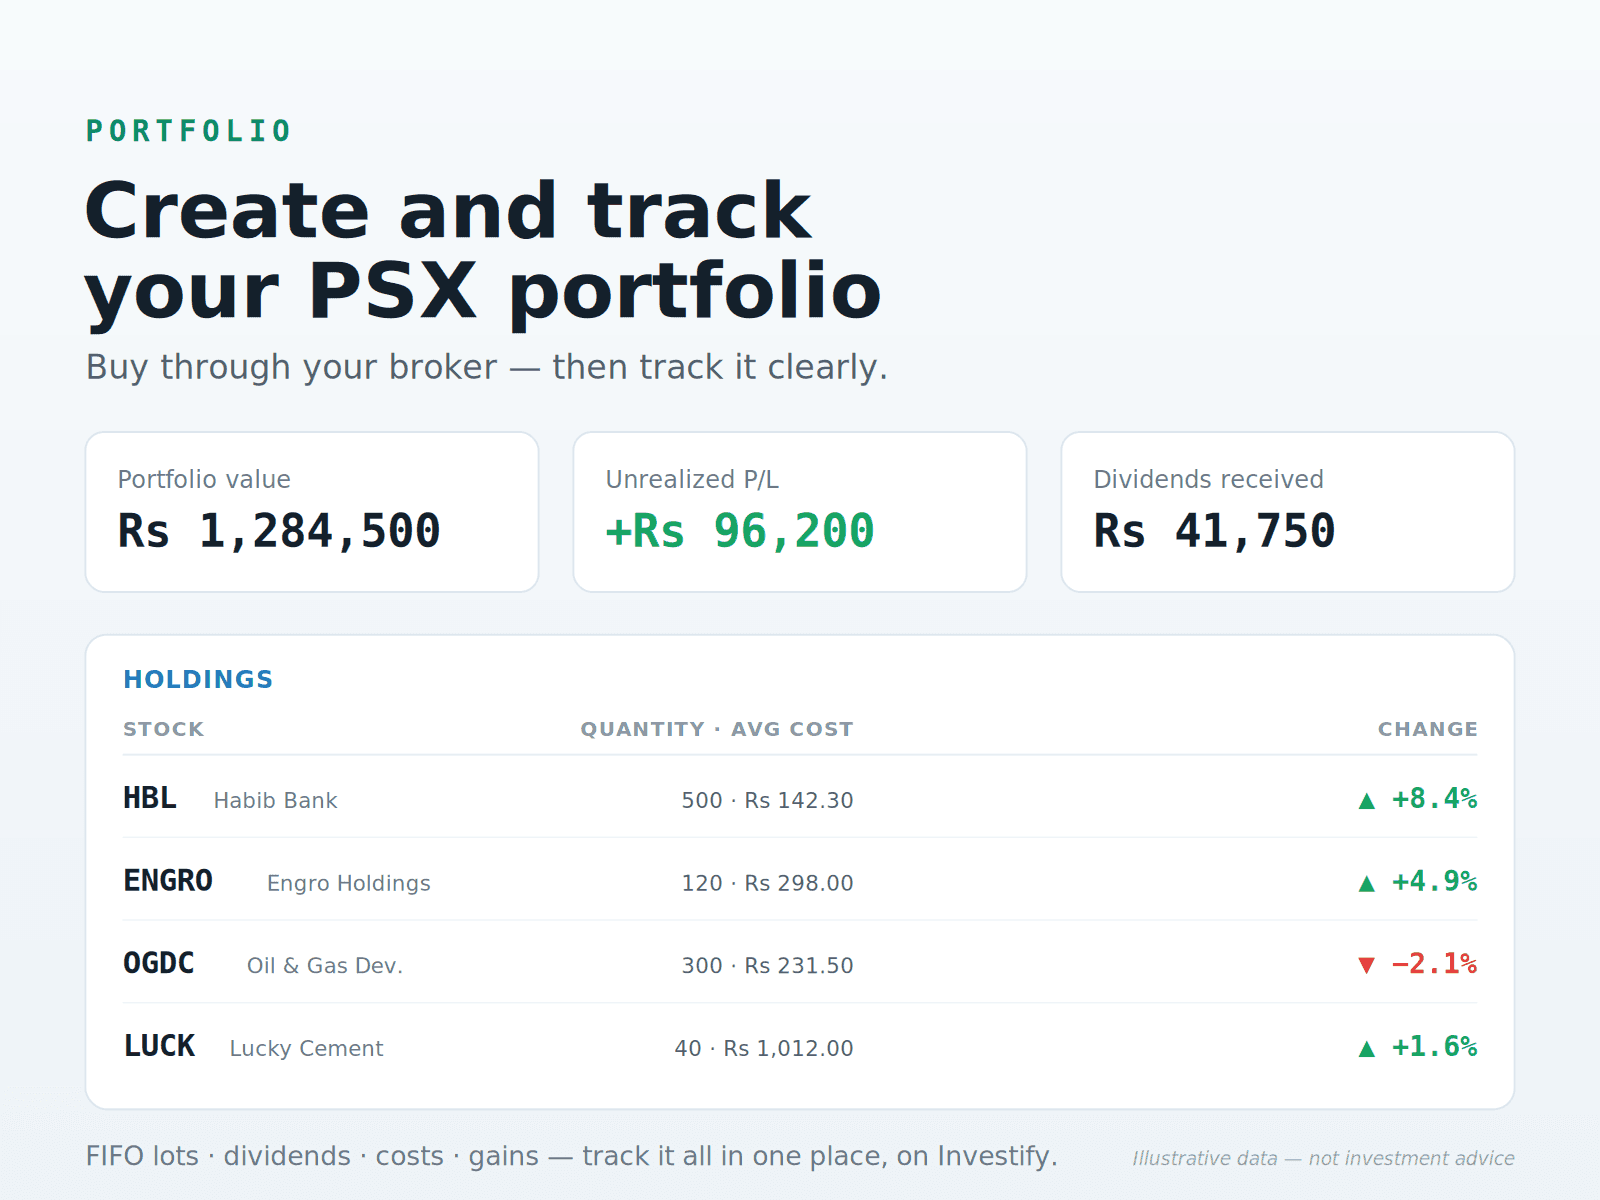
How to Create and Track a PSX Stock Portfolio
Learn how to create a PSX stock portfolio through a licensed broker and track it with FIFO, dividends, costs and corporate actions.
Read guide